Grand Haven, MI

Medicaid-Accepting Senior Living in Grand Haven

One medicaid-accepting community in Grand Haven, MI — with free, unbiased guidance from local advisors.

1
Community
1
Medicaid Accepted
$4,600
Avg. Monthly Pricing

Explore Medicaid-Accepting Senior Living in Grand Haven

One medicaid-accepting community to review, with free guidance from a local advisor.

View all communities in Grand Haven
Karla Middlecamp

Grand Haven Medicaid Advisor

Karla Middlecamp

Senior Care Consultant/Owner

Karla personally knows every medicaid-accepting community in Grand Haven. Get free, unbiased recommendations tailored to your family's care needs, budget, and timeline — no sales pressure, no obligations.

What to Expect From Medicaid-Accepting Senior Living in Grand Haven

  • Medicaid: All 1 community accepts Medicaid for residents who qualify.
  • Care types offered: assisted living.
  • Setting mix: 1 community in the matching set.

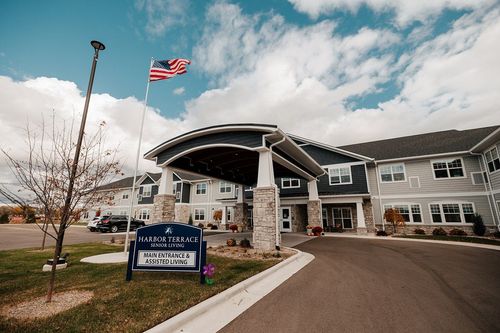
The question that stalls most Ottawa County households is not whether Medicaid exists but what has to happen to their savings first. Long-term-care Medicaid is means-tested, which means a household with a paid-off house on the north side of town, a modest retirement account and a life insurance policy is not simply eligible on the day it decides to apply. Robbinswood Assisted Living Community is the Grand Haven address carrying Medicaid acceptance, and getting a resident into it is as much a financial exercise as a placement one. Knowing what that exercise involves, and starting it early, is what separates a household that manages the transition from one that discovers the rules at the worst possible moment.

What the Program Pays For

Think of the monthly bill as two halves that are funded separately. One half is the help: someone assisting with a shower, a nurse keeping an eye on things, medications handled correctly. Michigan pays for that half through MI Choice for residents who qualify. The other half is board and lodging, the apartment and the food and the heat, and that half stays with the resident, met from a Social Security payment and whatever pension exists. Almost every unwelcome surprise later in the process traces back to a household believing the state was picking up both halves.

Which program applies also depends on where a resident lives. Assisted living and memory care are the waiver's territory, while a nursing facility is a different arrangement entirely, funded by traditional Medicaid, which is broader in what it takes on. Independent living qualifies for nothing at any income level, because every one of these programs is built on an assessed need for care and independent living has none to assess. So a building known as Medicaid-accepting is only ever describing a portion of what it does.

Assets, Spend-Down and the Look-Back

Eligibility turns on countable assets and monthly income, and the words doing the work there are countable and monthly. Some things a household owns are counted and some are not, a primary residence and a vehicle being treated differently from an investment account, and the details are specific enough that guessing is a poor strategy. Where assets exceed the limit, the household spends down toward it, which means using its own money on care and legitimate expenses until the threshold is met.

What catches people out is the look-back, which is the least intuitive rule in the whole scheme. Michigan reviews assets transferred or given away over a period of years before an application, and a gift made with the kindest intentions, a sum handed to a grandchild for a wedding or a house signed over to a son, can produce a penalty period during which the state pays nothing. That rule is why this is a planning matter rather than a paperwork one, and why a conversation two years before a move is worth incomparably more than one two weeks before.

What It Costs Locally

The published starting figure at the Grand Haven address carrying Medicaid acceptance is $4,600 a month, which is where private payment begins rather than what a waiver-funded resident is billed. On a fixed income the distance between that number and a monthly Social Security check is exactly the gap this whole process exists to close.

One Michigan provision is worth counting into that gap before anyone writes it off as unbridgeable. Where a resident lives in a licensed setting and draws federal disability income, the state adds a monthly payment on top of it, and that addition is aimed at precisely the half of the bill the waiver leaves alone. On its own it seldom finishes the job, and it is not meant to. It has decided plenty of cases where the shortfall was small enough for it to matter.

What an Advisor Handles in Ottawa County

With one Medicaid-accepting address locally, searching is not the task. What matters is sequence: does the building hold a waiver-funded place at the moment, will it admit somebody privately and move them onto the waiver afterward, and at what stage of the regional process does either answer start to mean anything.

An advisor covering Ottawa County holds those answers, and will also say plainly when the more useful call is to an elder law attorney instead, which is the honest recommendation wherever a house or a substantial gift sits anywhere in recent history. Getting that order right at the beginning is worth considerably more than any list of addresses, and there is no cost to talk it through before decisions start being made under pressure.

Our directory for Grand Haven continues to grow as we evaluate providers for quality and alignment in 2026. Start the conversation about medicaid in Grand Haven, or scan the buildings we cover at your own pace.
Karla Middlecamp

Karla Middlecamp

Senior Care Consultant/Owner, Michigan

Advisor Insight on
Medicaid in Grand Haven

Long-term-care Medicaid in Michigan is means-tested, and the rule that catches Ottawa County households is the look-back on assets given away in the years before an application. A house signed over to a son, or a sum handed to a grandchild, can create a penalty period during which the state pays nothing, which is why this is a planning matter rather than a paperwork one.

Medicaid-Accepting Senior Living Near Grand Haven

Medicaid communities within 25 miles of Grand Haven.

Frequently Asked Questions About Medicaid-Accepting Senior Living in Grand Haven

What are the asset limits for Medicaid in Michigan?

Michigan sets a limit on countable assets and a separate treatment of monthly income, and the useful word in that sentence is countable. Not everything a household owns is counted: a primary residence and a vehicle are handled differently from an investment account or a second property, and certain prepaid funeral arrangements sit outside the calculation entirely. The thresholds are adjusted periodically, so a figure someone heard from a neighbor is not a safe basis for planning. Where countable assets exceed the limit, a household spends down toward it by paying for care and legitimate expenses out of its own funds.

What is the Medicaid look-back period?

It is the stretch of time before an application during which Michigan examines assets that were transferred, sold below value or given away. The point is to identify money moved specifically to qualify, but the rule does not test intention, so a gift made for entirely loving reasons is caught the same way a deliberate transfer would be. Where the state finds one, it imposes a penalty period, a stretch during which it will not pay, calculated from the value moved. This is the single strongest argument for taking advice years before it is needed rather than weeks.

Can a family keep the house and still qualify for Medicaid?

Often, at least during the resident's lifetime, and the detail matters too much to summarize safely. A primary residence receives different treatment from other assets, particularly where a spouse continues to live in it, and different rules again may apply to a home standing empty. Separately, Michigan operates estate recovery, meaning the state can seek repayment from an estate after death, and a house is usually the largest thing in one. Because the interaction of those rules turns on specifics, a household with property should be speaking to an elder law attorney rather than working from general guidance.

Does the healthy spouse lose everything?

No, and this is the fear that most often prevents families from asking at all. Medicaid rules include protections for a spouse who remains at home, allowing that person to retain a share of the couple's assets and, in some circumstances, a portion of the applicant's income, so that one partner needing care does not leave the other destitute. The amounts involved are set by formula, adjusted periodically, and depend on the couple's particular finances. What is worth knowing at the outset is simply that the protection exists, because assuming otherwise leads households to delay applying long past the point where they should have.

How long does Medicaid approval take in Michigan?

Longer than households allow for, and the reason is that two processes have to finish and they run independently. The financial side means proving income, listing what is owned and accounting for anything given away or sold cheaply within the look-back window, and the slow part of that is almost always waiting on banks, pension administrators and a register of deeds rather than anything the state does. The care side means an assessment being scheduled and carried out to establish that the need genuinely reaches the required threshold. Clearing both still leaves the question of whether a waiver place exists, since enrollment is capped. Beginning well before a room is wanted is the only real remedy.

More Senior Living in Grand Haven

Get Help Finding Medicaid-Accepting Senior Living in Grand Haven

Our local advisors know every medicaid-accepting community in Grand Haven personally. Get free, unbiased recommendations tailored to your family's care needs, budget, and location preferences.

Free service · No obligation · We only recommend what's right for you